

Weekly Newsletter August 24th to August 28th
RECAPPING LAST WEEK
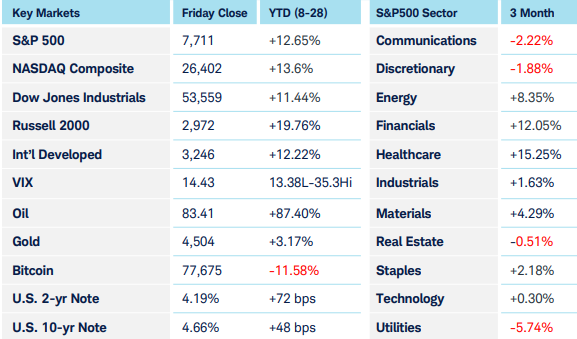
Global markets were relatively quiet this past week with most major macro asset classes modestly reversing some of the prior week’s sharper moves in a quiet consolidation. The S&P 500 and Nasdaq 100 each rose about a half of a percent, while the small-cap Russell 2000 fell 1.5%. The tone in equities was helped by a combination of a slight reduction in Treasury yields on the long end of the curve, declining oil prices, and a very strong earnings report from Nvidia. Treasuries remained the most important macro story after the sharp rise in yields on the long end of the curve the prior week led the Treasury to announce its intent to increase its purchases of longer-dated Treasuries, complicating the picture for Fed Chair Warsh’s expressed desire to use market signals to help guide policy rather than strictly being data-dependent. Stan Druckenmiller, former colleague of Treasury Secretary Bessent at Soros Fund Management, and later employer of now Fed Chair Warsh at his Duquesne Family Office, drew widespread attention to this issue with his Wall Street Journal op-ed entitled “Let the Bond Market Speak” whereby he firmly rebuked the Treasury’s action as interfering with those very market signals that should be guiding not just Fed policy, but fiscal policy and investor decision making. In Warsh’s widely anticipated speech at the Fed’s Jackson Hole symposium, the Chair provided an additional look at some of those market signals he follows, from credit spreads to the AI economy’s pricing of “tokens” to access the various models, while ultimately reiterating that he still views the Fed Funds target rate as their main inflation fighting tool. With the acknowledgement that inflation still isn’t where the Fed wants it to be, markets went from pricing in a 35% chance of a hike at the September meeting to a 55% chance. Nvidia’s blowout second quarter, in which it announced revenue of $96.2 billion, up 106% from a year earlier, also temporarily put aside concerns about capex spending going forward when they guided market expectations towards third-quarter revenue of $104 billion. The AI firms versus traditional software story was also reset this week when Salesforce not only announced strong earnings but also a collaboration with Anthropic whereby their systems would be embedded within each other. Enterprise software firms, whose stocks were punished earlier in the year off fears of impending irrelevance, were some of the strongest performers for the week. The U.S. military’s Central Command reported that the Strait of Hormuz was now free of mines and that 1500 vessels carrying approximately 750 million barrels of crude oil have now successfully transited the Strait. The subsequent modest decline in oil prices and refining margins saw the Energy Sector give back 1.5% for the week. The market response to the increased odds of the September rate hike saw the Dollar rally on Friday and gold slip from its recent highs while cryptocurrencies remained firm after their spectacular rally of the week prior.
THE WEEK AHEAD
As we head into the last week of traditional summer ahead of the Labor Day weekend, once again the markets will have to wait until Friday for the main event, in this case the August Employment Report. After July’s surprising read, which showed a decline of 23k jobs, payrolls are expected to recover by a modest 56k with the unemployment rate holding steady at 4.1%. Although inflation has captured market attention—especially amid debate over whether one-time shocks from tariffs or energy prices could shift long-term expectations—employment remains the other side of the Fed’s dual mandate, as the Chair was careful to note. Friday’s report will shed some light on whether July’s decline was a one-off in an overall healthy labor market or the canary in the coal mine.
CHART OF THE WEEK
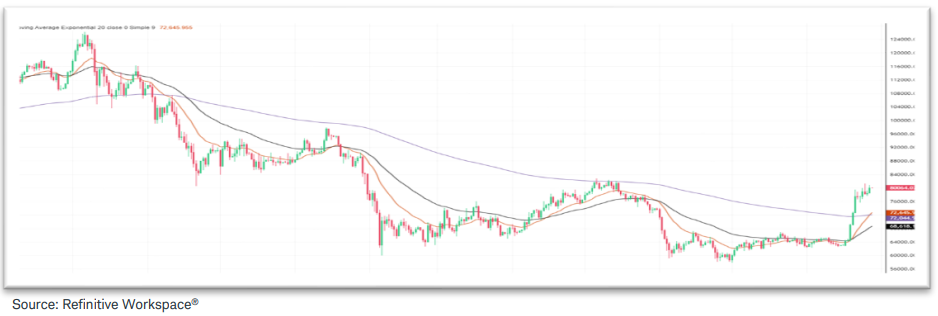
Make Crypto Rally Again
Crypto markets have had a rough year with Bitcoin cutting its price in half and many other coins getting hit even worse. The downward trend stalled out in early June, and although it didn’t reverse to an uptrend, prices did stop dropping and sat still over the next two months, an incredibly tight range which was unusual for bitcoin. That finally changed two weeks ago when a slew of bullish announcements came in rapid-fire, sparking a 30% rally in bitcoin, 35% in Ethereum, and 50% in Solana since. The SEC proposed “Regulation Crypto Assets” offering a framework for the industry and defining registration, disclosure, and fundraising pathways. Two days later, the CFTC followed suit, exploring a federal crypto-market framework, one of the main goals of the ever-elusive CLARITY Act now set for a vote in September, utilizing its existing authority. This was not, however, the most important catalyst pressing crypto higher. The day between those two announcements, Treasury Secretary Bessent announced it would at least double the size of its buybacks of longer-dated Treasuries, pressing longer-term yields and the dollar lower, both pushing capital to inflation and debasement hedges like gold and crypto. Pouring gas on the fire, President Trump hosted several crypto executives at the White House and urged Congress to pass the CLARITY Act. ETF inflows hit levels not seen since the highs last October, and positioning was overwhelmingly bearish prior to those announcements, so the subsequent price rally triggered liquidations of stretched short positions, causing $1.2 billion in short covering liquidations within an hour, and $1.6 billion over the week. The persistent bearish sentiment clouding crypto markets since October is finally turning.
Source: Charles Schwab Corporation
IMPORTANT LEGAL NOTICE AND DISCLOSURE INFORMATION
Investment advisory service is provided by SVL Holding Corporation dba SVL Investments Management (“SVL”), a California registered investment advisor. Advisory services are subject to advisory fees as disclosed on Form ADV.
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets.
Past performance may not be indicative of future results. Therefore, no current or prospective client should assume that future performance of any specific investment, investment strategy (including the investments and/or investment strategies recommended or undertaken by SVL) or product made reference to directly or indirectly by SVL in its web site, or indirectly via a link to an unaffiliated third party web site, will be profitable or equal the corresponding indicated performance level(s). Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product (including the investments and/or investment strategies recommended or undertaken by SVL), or any non-investment related content, made reference to directly or indirectly on this site will either be suitable or profitable for a client or prospective client’s investment portfolio. Historical performance results for investment indices and/or categories generally do not reflect the deduction of transaction and/or custodial charges, the deduction of an investment management fee, or the impact of taxes, the incurrence of which would have the effect of decreasing historical performance results for investment indices.
Certain portions of SVL‘s web site (i.e. blog, Insights, newsletters, articles, commentaries, etc.) may contain a discussion of, and/or provide access to, SVL‘s (and those of other investment and non-investment professionals) positions and/or recommendations as of a specific prior date. Due to various factors, including changing market conditions, such discussion may no longer be reflective of current position(s) and/or recommendation(s). Moreover, no client or prospective client should assume that any such discussion serves as the receipt of, or a substitute for, personalized advice from SVL or from any other investment professional. SVL is neither an attorney nor accountant, and no portion of the web site content should be interpreted as legal, accounting or tax advice.
Rankings and/or recognition by unaffiliated rating services and/or publications should not be construed by a client or prospective client as a guarantee that he/she will experience a certain level of results if SVL is engaged, or continues to be engaged, to provide investment advisory services, nor should it be construed as a current or past endorsement of SVL by any of its clients. Rankings published by magazines, and others, generally base their selections exclusively on information prepared and/or submitted by the recognized adviser.
To the extent that any client or prospective client utilizes any economic calculator or similar device contained within or linked to SVL‘s web site, the client and/or prospective client acknowledges and understands that the information resulting from the use of any such calculator/device, is not, and should not be construed, in any manner whatsoever, as the receipt of, or a substitute for, personalized individual advice from SVL, or from any other investment professional.
Each client and prospective client agrees, as a condition precedent to his/her/its access to SVL‘s web site, to release and hold harmless SVL, its officers, directors, owners, employees and agents from any and all adverse consequences resulting from any of his/her/its actions and/or omissions which are independent of his/her/its receipt of personalized individual advice from SVL.