

Weekly Newsletter September 28th to October 2nd
RECAPPING LAST WEEK
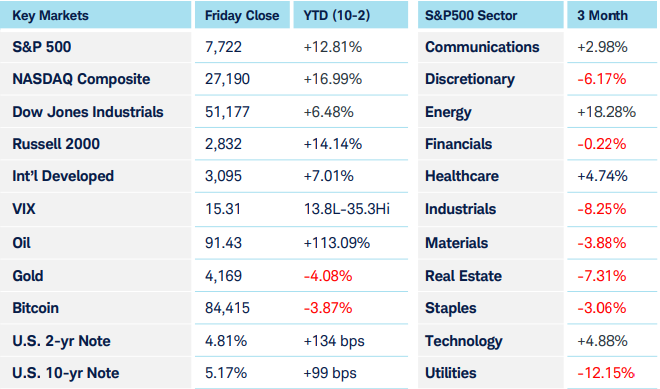
Global equity markets remained resilient last week despite another sharp rise in Treasury yields, with the 10-year yield surging to 5.34%, its highest level since 2002, before pulling back following Friday’s benign employment report. The rise in yields reflected persistent inflation concerns, elevated energy costs and increasing expectations that interest rates will remain higher for longer. The move was not confined to the U.S., with European bond markets also under pressure as the French 10-year vs. German 10-year spread widened to over 150 basis points. While the U.S. Dollar continues to benefit from the widening yield differentials, the intra-Europe turmoil driven by French fiscal issues led to a sharp selloff in the Euro, notably against the zero-interest-ratebearing Swiss Franc, which resumed its historical role as a “flight to quality” instrument. Energy prices provided some relief late in the week after the G-7 countries agreed to release 100 million barrels of crude oil and diesel from their strategic reserves. This came after reports that the Trump administration had been pressuring European countries to do so with the threat of the U.S. implementing a ban on diesel exports. China did in fact implement an export ban on refined petroleum products, reflecting the continued constraints on refining capacity and delivery being felt globally. In U.S. equities, mega-cap tech propelled the Nasdaq 100 into all-time highs, led by market cap leader Nvidia and buoyed by accelerating record earnings out of Micron. Short-term interest rate markets also didn’t need to await the release of Friday’s employment report to adjust expectations of Fed policy as the chance of a rate hike at the October meeting was steadily reduced throughout the week from 64% to only 18%. Helping along the way was the mid-week release of the Personal Consumption Expenditures index—which we all know is “The Fed’s Preferred Inflation Gauge.” The annualized rate came in at 3.0%, a tenth below the low-end of market expectations and 1% away from the Fed’s stated target. The employment report showed considerably weaker job creation than expected. September payrolls increased only 29k, versus expectations of 85k, while the unemployment rate up ticked a tenth to 4.2%. The knee-jerk reaction to the release of the data was a rally in stocks, bonds, precious metals and crypto, and a decline in the dollar amid lessened expectations of an urgency for the Fed to hike rates. However, the reaction was short-lived as all the asset classes soon reversed course—with the exception of the ever-resilient tech-heavy equity indices.
THE WEEK AHEAD
The U.S. fixed income markets will get a test of the market’s appetite for longer-dated issues as the Treasury conducts their monthly auction for 10-years and 30-years on Wednesday and Thursday, respectively. The Bank of Japan will also be issuing 10-and 30-year JGBs next week and investors will surely be keeping an eye on whether the blowout in spreads between French and German debt has the sort of aftermath of similar instances on European sovereign debt spread divergences. The minutes from the Fed’s September meeting will also be released on Wednesday and should provide additional insight into the policymakers’ views on dealing with still elevated inflation. The mega-cap techs seem least concerned with the rise in yields as the expectations of returns on their AI investments are overshadowing the elevated funding costs as a mere inconvenience. But behind the tech-dominated index numbers, there’s certainly a divergence between the chipmakers who have been the real-time beneficiaries of all the spending and the hyperscalers who have tapped the credit markets to the tune of $220B this year. It’s the former who have driven the Nasdaq 100 to new highs while the latter group has lagged. One may think a little concern for the elevated levels is being expressed in the options market as well as the spread between implied volatility of 30-day Nasdaq 100 options (VXN) and S&P 500 options (VIX) reversed course from its steady narrowing since mid-June to widening out this past week. Of course, one also observes that this spread widened out considerably when the chipmakers had their historic run during April and May.
CHART OF THE WEEK
Margins of Concern
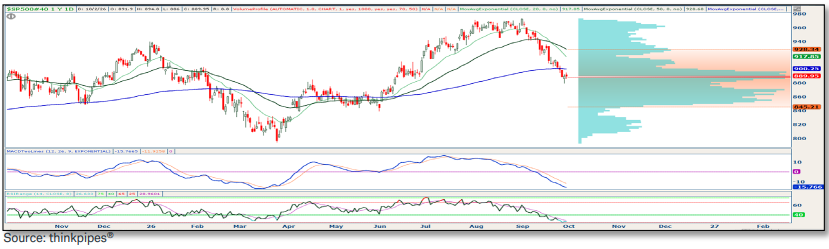
The U.S. S&P Financials Sector Index ($SP500#40) has been the worst-performing S&P 500 sector over the last month, dropping 10% from the 9/3 high to last week’s low on the back of interest rates continued march higher. Higher rates pose both risks and opportunities for financial institutions depending on how fast the rates increase, and the situation of the institution. If income from floating-rate loans rises faster than their cost of capital, it’s a net benefit, along with insurance companies’ ability to invest premiums at more attractive yields. Yet that’s not always the case, as rate increases also raise their cost of capital, slow demand for loans due to increased interest expense, and weaken the strength of borrowers, thereby increasing default rates. Interest rates and existing bond prices are inversely correlated, so this environment puts significant pressure on the valuation of bonds already on the books. We saw a clear example of this in 2022, causing three bank failures in 2023 from the depreciation in their bond portfolios. We’re not at that level of concern yet, and although credit spreads have been surprisingly tight until now, last week’s expansion showed growing concerns. From a technical perspective, momentum is still pointed lower from several moving averages along with the MACD at yearly lows. That said, price has arrived at a stronger support level at $890, and the RSI is well into oversold territory, offering an ideal spot to find relief. If that bounce arrives, its ability to continue could chart the path into year-end.
Source: Charles Schwab Corporation
IMPORTANT LEGAL NOTICE AND DISCLOSURE INFORMATION
Investment advisory service is provided by SVL Holding Corporation dba SVL Investments Management (“SVL”), a California registered investment advisor. Advisory services are subject to advisory fees as disclosed on Form ADV.
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets.
Past performance may not be indicative of future results. Therefore, no current or prospective client should assume that future performance of any specific investment, investment strategy (including the investments and/or investment strategies recommended or undertaken by SVL) or product made reference to directly or indirectly by SVL in its web site, or indirectly via a link to an unaffiliated third party web site, will be profitable or equal the corresponding indicated performance level(s). Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product (including the investments and/or investment strategies recommended or undertaken by SVL), or any non-investment related content, made reference to directly or indirectly on this site will either be suitable or profitable for a client or prospective client’s investment portfolio. Historical performance results for investment indices and/or categories generally do not reflect the deduction of transaction and/or custodial charges, the deduction of an investment management fee, or the impact of taxes, the incurrence of which would have the effect of decreasing historical performance results for investment indices.
Certain portions of SVL‘s web site (i.e. blog, Insights, newsletters, articles, commentaries, etc.) may contain a discussion of, and/or provide access to, SVL‘s (and those of other investment and non-investment professionals) positions and/or recommendations as of a specific prior date. Due to various factors, including changing market conditions, such discussion may no longer be reflective of current position(s) and/or recommendation(s). Moreover, no client or prospective client should assume that any such discussion serves as the receipt of, or a substitute for, personalized advice from SVL or from any other investment professional. SVL is neither an attorney nor accountant, and no portion of the web site content should be interpreted as legal, accounting or tax advice.
Rankings and/or recognition by unaffiliated rating services and/or publications should not be construed by a client or prospective client as a guarantee that he/she will experience a certain level of results if SVL is engaged, or continues to be engaged, to provide investment advisory services, nor should it be construed as a current or past endorsement of SVL by any of its clients. Rankings published by magazines, and others, generally base their selections exclusively on information prepared and/or submitted by the recognized adviser.
To the extent that any client or prospective client utilizes any economic calculator or similar device contained within or linked to SVL‘s web site, the client and/or prospective client acknowledges and understands that the information resulting from the use of any such calculator/device, is not, and should not be construed, in any manner whatsoever, as the receipt of, or a substitute for, personalized individual advice from SVL, or from any other investment professional.
Each client and prospective client agrees, as a condition precedent to his/her/its access to SVL‘s web site, to release and hold harmless SVL, its officers, directors, owners, employees and agents from any and all adverse consequences resulting from any of his/her/its actions and/or omissions which are independent of his/her/its receipt of personalized individual advice from SVL.